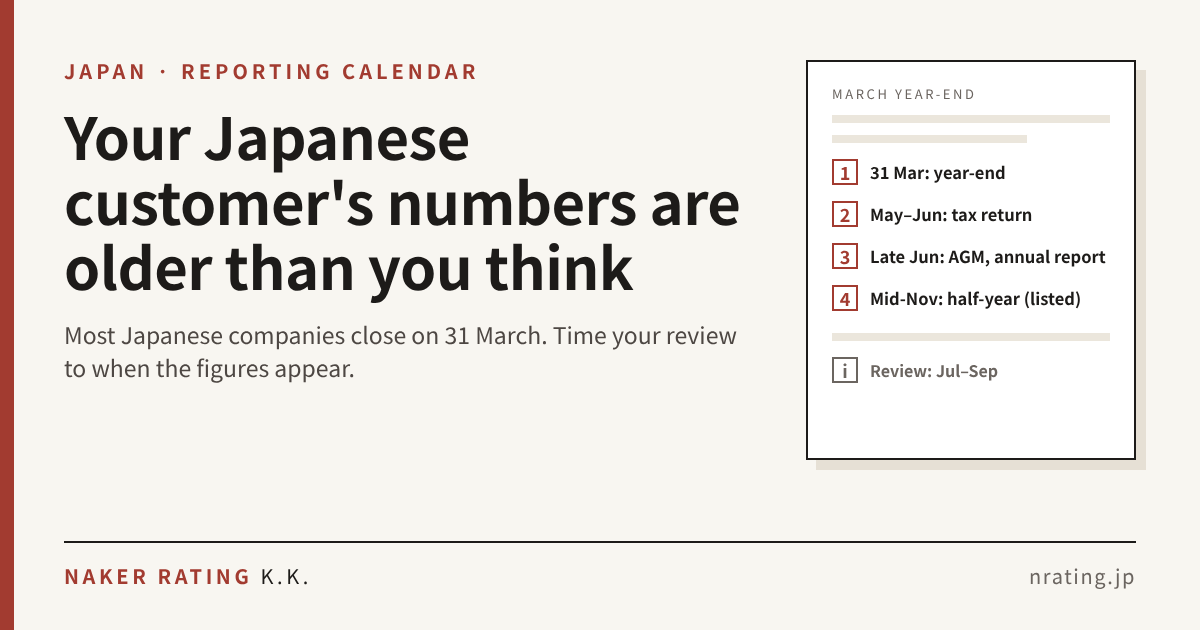
- 1March year-endsMany Japanese companies close their books on 31 March, in line with the government fiscal year
- 2Listed companiesResults summaries in spring, the annual report within three months and, since 2024, a half-year report within 45 days of the half-year end
- 3Private companiesNo duty to send you their accounts. Their figures are rarely available before the summer
- 4When to reviewThree to five months after the year-end: for March year-ends, July to September
- 5What to recordThe period your figures cover, not only the report date. Treat late figures as information
Many credit teams outside Japan review their customers on a calendar-year cycle. Many Japanese companies close their books on 31 March. Put the two together and you get a familiar problem: the “latest” accounts for a Japanese customer, reviewed in February, are for a year that ended almost eleven months earlier, and the next set will not appear for several months more.
This article explains when Japanese companies’ figures actually become available, what that means for your review cycle, and what to look at in the gap.
Why March
Japan’s government fiscal year runs from 1 April to 31 March, and a large part of corporate Japan follows the same year. In 2026, more than 2,100 listed companies with a March year-end announced the date of their annual shareholders’ meeting by the end of May, and almost a third of them held it on the same day, 26 June.
Not every Japanese company uses March. December year-ends are also common, and other month-ends are used in some sectors. The first thing to record for any Japanese customer is its own year-end.
When the numbers arrive
For a company with a 31 March year-end, the calendar usually looks like this:
- April to May: listed companies’ results summaries. Listed companies publish a summary of their annual results (kessan tanshin) through the stock exchange’s disclosure system.
- End of May, or end of June: the tax return. A Japanese corporate tax return is due within two months of the year-end. Companies whose shareholders’ meeting is not held within two months can extend the deadline, usually by one month.
- Late June: the shareholders’ meeting and the annual report. Listed companies must file their annual securities report within three months of the year-end. Voting rights are usually fixed at the year-end, and the law limits how long that record date can be used to three months, which is one reason so many meetings are held in late June.
- After the meeting: the published balance sheet. Stock companies must publish their balance sheet without delay after the annual meeting. As we explained in our article on the Japanese registry, many small companies do not.
- Mid-November: half-year figures (listed companies). Since April 2024, listed companies no longer file quarterly securities reports. They file a half-year report within 45 days of the half-year end, and publish first- and third-quarter results only as exchange summaries. For a March year-end company, the half-year ends on 30 September, so its half-year report appears by mid-November.
Private companies have no obligation to send their accounts to you, and many never publish them. In our experience, the figures of a private company with a March year-end are rarely obtainable before the summer.
What this means for your review
A spring review uses old figures. If you review a March year-end customer in January to March, you are working with figures for a year that ended ten to twelve months earlier. Nothing newer will be available for another three to five months.
The best time is three to five months after the year-end. For March year-ends, that means July to September. If your cycle cannot move, at least make sure your file records which period the figures cover, not only the date of the report.
Between reviews, ask for interim figures. For a listed customer, the half-year report is public. For a private customer with a large exposure, it is reasonable to ask for its latest monthly trial balance (shisanhyo). Many Japanese companies prepare one each month.
Check the length of the period. A company that changes its year-end reports an irregular period, often shorter than twelve months. Comparing a nine-month period with a twelve-month one will make sales look as if they have collapsed.
Treat a late filing as information. A listed company that announces it cannot file its annual securities report on time, or a private company that normally publishes and then stops, deserves a question. So does a customer that suddenly cannot provide figures it used to provide.
Filling the gap
Financial statements are only one part of a credit assessment, and for most of the year they are out of date. Between year-ends, the useful signals are elsewhere:
- Payment behaviour: your own ledger, and any change in how promptly the customer pays.
- Registry changes: new directors, a moved head office, a capital reduction.
- Official notices: bankruptcy, liquidation and capital-reduction notices in the Kanpo, as described in our article on the Official Gazette.
- Litigation and news: lawsuits, regulatory action, the loss of a major customer.
A simple routine
- Record each Japanese customer’s year-end. Do not assume March.
- Schedule the annual review three to five months after it.
- Record the period the figures cover, and flag anything older than fifteen months.
- For larger exposures, ask for interim figures between reviews: the half-year report for listed companies, a recent trial balance for private ones.
- Check for irregular periods before comparing years.
- Ask when figures are late, and lower your confidence until you have an answer.
How we help
Naker Rating K.K. investigates Japanese companies for credit managers, trade-credit insurers and credit-reporting agencies outside Japan. Our English-language reports state the fiscal year-end and the period of the figures used, and combine financial analysis with payment, registry, public-notice, litigation and adverse-record checks. Each report gives a five-grade credit rating (NRating), an estimated default probability and a credit limit (NR Credit Limit). When a company publishes no accounts at all, our reports include NRMFS, our estimated financial statements, so you still have reference figures for its size, net worth and leverage.
You can see two actual reports, de-identified, in our sample pack.
Download the sample pack (PDF) | Order a report by email | Ask about a Japanese company
Summary
- Many Japanese companies close their books on 31 March, in line with the government fiscal year.
- Listed companies publish results summaries in spring, file their annual report within three months and, since 2024, a half-year report within 45 days of the half-year end.
- Private companies have no duty to send you their accounts, and their figures are rarely available before the summer.
- Review March year-end customers three to five months after the year-end, record the period your figures cover, and treat late figures as information.
Sources
- Public Finance Act, Article 11 (government fiscal year) (財政法第11条): https://laws.e-gov.go.jp/law/322AC0000000034
- Tokyo Stock Exchange, dates of annual shareholders’ meetings of companies with March 2026 year-ends (2026年3月期決算会社の定時株主総会開催日の集計結果): https://www.jpx.co.jp/news/1021/20260605-01.html
- Financial Instruments and Exchange Act, Article 24 (annual securities report) and Article 24-5 (half-year report) (金融商品取引法第24条・第24条の5): https://laws.e-gov.go.jp/law/323AC0000000025
- Financial Services Agency, abolition of quarterly securities reports from 1 April 2024 (四半期報告書制度の廃止に伴う政令・内閣府令等の整備): https://www.fsa.go.jp/news/r5/sonota/20231208/20231208.html
- Corporation Tax Act, Article 74 (filing deadline) and Article 75-2 (extension) (法人税法第74条・第75条の2): https://laws.e-gov.go.jp/law/340AC0000000034
- Companies Act, Article 124 (record date), Article 296 (annual shareholders’ meeting) and Article 440 (public notice of balance sheet) (会社法第124条・第296条・第440条): https://laws.e-gov.go.jp/law/417AC0000000086